

Payactiv
On-demand pay and beyond
- 4.5
- 8.37K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
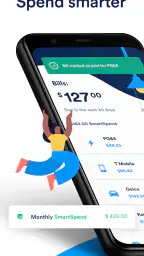
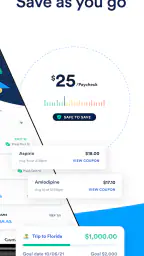
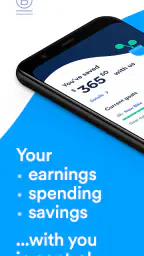
Payactiv Pros and Cons
Pros
- Easy access to earned wages
- No credit check required
- User-friendly interface
- Supports financial wellness
- Instant transfer to bank
Cons
- Fees for instant transfers
- Limited to partnered employers
- Not a full replacement for paycheck
- Potential dependency risk
- Requires bank account setup
 Analysis by All-app
Picture this: It’s the middle of the month, and you’re pinching pennies to make it to payday. We’ve all been there, right? Well, I’ve stumbled upon an app that might just be the knight in shining armor for those of us who find ourselves in this predicament. Let me introduce you to Payactiv, an app that promises to turn your financial frown upside down.
Where the app fits today
I see Payactiv as a finance app for people whose main problem is timing rather than a lack of income: the bills arrive before the next payday, even though some of the wages to cover them have already been earned. Its central idea is to make that earned pay accessible earlier, which can be useful for a short-term cash-flow gap. It is not the same thing as a new source of income, and I would not treat an early withdrawal as extra money.
The app is free to download, is rated for Everyone, and is developed by On-demand pay and beyond. It has a 4.5 average from around 40,000 ratings, with more than a million installs. Those figures suggest that many people have tried it, but they do not tell me whether the service fits a particular workplace or how a given user’s access will work. The practical starting point is whether your employer’s payroll setup supports it.
That distinction matters more than the friendly framing around financial wellness. If early access simply moves part of a paycheck forward, the next regular payday may leave less money available than usual. I would use the app to solve a defined timing problem, then check how the following pay period looks before making the same choice again.
How early access changes the payday routine
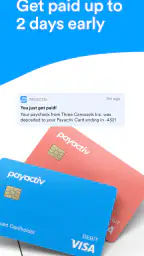
So, what exactly is this app all about? In simple terms, it’s a financial wellness app that offers a variety of services to help you manage your money better. The app essentially allows users to access their earned wages before payday, and that’s just the tip of the iceberg. Imagine being able to tap into your earnings at any time to pay for unexpected expenses without having to resort to high-interest payday loans.
Features that make a difference
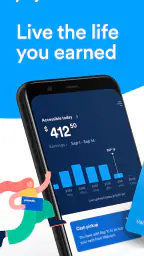
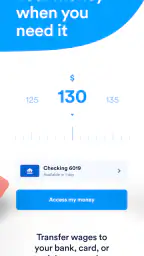
One of the standout features of the app is its Earned Wage Access. This feature lets you access a portion of your earned wages whenever you need it. You no longer have to wait for your paycheck to hit your bank account to tackle those emergency expenses. Additionally, the app offers a savings tool which is super handy for those of us who need a little nudge to save for a rainy day.
Another cool feature is the app’s financial counseling services. It’s like having a financial advisor in your pocket, ready to offer guidance and tips to improve your financial health. Whether you need advice on budgeting or managing debt, the app’s got you covered.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What a realistic week could look like
Imagine a necessary expense landing a few days before payday, while you know you have already worked enough hours to cover it. I would first compare the bill’s due date with the next paycheck and decide whether paying early is genuinely necessary. If it is, an advance may help bridge that specific gap. I would then write down the amount taken early and treat it as money already spent, rather than relying on the next paycheck to feel normal.
That small habit is important because access can make money feel more available than it is. A useful approach is to reserve early access for a bill or urgent purchase, not use it for routine extras, and check the next pay cycle before repeating the decision. The savings tool may also be more useful as a gradual habit than as a quick fix: setting aside a manageable amount when things are stable can reduce the chance of needing an advance later.
People often wonder whether an app like this replaces a budget. In my view, it does not. It can help with the timing of wages, while a simple written plan still helps you see rent, bills, food, transport, and the amount left for the rest of the pay period. If the shortfall happens every month, tracking those dates and amounts can show whether the core issue is timing or that regular expenses are exceeding income.
Using it without losing track of the next payday
Alright, now let’s talk about the user experience. Navigating through the app is a breeze, thanks to its intuitive design. The layout is clean, making it easy for users to find what they need without unnecessary fuss. Plus, the app is available on both Android and iOS, so it’s accessible to a wide range of users.
What I particularly love about the app is how it simplifies the process of managing finances. The app integrates seamlessly with your employer’s payroll system, ensuring that everything runs smoothly without you having to lift a finger. It’s like having a personal finance assistant that takes care of all the nitty-gritty details for you.
In practice, payroll integration is also the first thing I would check before relying on it for a deadline. An employee should confirm that their workplace is supported and allow time to understand how access relates to hours worked and the normal pay cycle. If you are new to a job, changing employers, or working irregular hours, avoid assuming that access will be available on the schedule you expect until the app and employer arrangement show that it is.
Another practical question is whether it is a good fit for every worker. I would consider it most useful for someone with steady work and a temporary mismatch between earned pay and bill dates. Someone with unpredictable hours may find planning harder, while a person who can comfortably wait for payday may prefer to leave the paycheck untouched. It is also not the right answer to a recurring debt problem by itself; counseling and a clearer budget may help, but neither can make an unaffordable pattern disappear overnight.
How it compares with other ways to cover a gap
Compared with a payday loan, earned-wage access is based on pay already earned rather than borrowing against future income in the usual way. That makes the concept appealing when the need is brief and the amount is limited. Still, I would compare the actual terms and the effect on the next paycheck before choosing any service. “Earlier access” is not automatically cost-free or consequence-free in every situation, so the decision should be based on what the app presents to you, not on the label alone.
A credit card can be more convenient for a purchase if the balance can be paid off promptly, but carrying debt may become expensive. An overdraft may cover a payment automatically, yet it can also create fees or a negative balance. Asking a bill provider about a due-date change or payment arrangement may be a better first move when the expense is predictable. Those options solve different problems; I would choose the one that leaves the clearest, least stressful path through the next pay cycle.
Payactiv’s distinguishing appeal is the connection between earned wages and payroll, alongside tools such as savings and counseling. For someone whose employer supports that arrangement, the combination may be more relevant than a general budgeting app that only tracks spending. For someone seeking investment features, broad account aggregation, or a standalone loan, it is not a substitute for those services.
What changed, and what existing users should take from it
The app was released on June 4, 2014, and its current version is 2.2.2. Those details place it as an established product with a defined current version, but they do not by themselves show which features changed between releases. I would not read a version number as proof of a particular redesign or new capability. For someone already using it, the sensible approach is to judge the tools currently visible in the app and whether they still fit the person’s payroll arrangement and financial routine.
If you are returning after time away, take a moment to review your available options and any amounts shown before acting. Your own work situation may have changed even if the app feels familiar: a new employer, different hours, or a new bill schedule can alter whether early access makes sense. Existing users should also avoid treating past availability as a promise that every future pay period will look the same.
For a new user, the question is less “Does the app have early access?” and more “Will this specific access solve my problem without creating a worse one next week?” I would start with one concrete need, check the amount and timing presented, and make a plan for the reduced balance on payday. If anything in the process is unclear, it is better to pause and clarify it than to tap through because a bill feels urgent.
The limits I would keep in mind
The biggest limitation is that this kind of service depends on the relationship between the user’s work and payroll. If an employer is not supported, or the person’s pay situation does not provide dependable access, the central benefit may not be available in a useful way. The app cannot make wages arrive sooner in the broader sense; it changes when a portion of earned wages can be reached.
I would also resist using it as a standing solution for a budget that never balances. Repeatedly moving money forward can make the next payday feel tight and leave little room for an unexpected cost then. In that situation, financial counseling may offer a place to think through options, but users may also need help from a qualified adviser or a trusted local service, depending on the problem. The app is a tool, not a guarantee of financial stability.
People considering it may also ask whether it is suitable for a first-time user, whether it replaces a bank account, or whether it can handle every emergency. I would not assume any of those things. It is best understood as an app for accessing earned pay and pursuing financial wellness goals; it is not a universal banking replacement, and it cannot resolve every kind of urgent expense. Read the choices shown in your own account carefully and use another option if it better fits the need.
Who I would recommend it to
I would suggest giving the app a look if your employer supports it, you have a specific short-term cash-flow squeeze, and you are comfortable planning around a smaller later paycheck. It may be especially helpful when a necessary bill falls just before payday and waiting would create a real problem. The savings and counseling elements could also be useful for someone trying to build steadier habits rather than relying only on early access.
I would skip it if your income is so irregular that you cannot confidently plan for the next check, if you are looking for a loan or a full-featured banking service, or if early access would simply fund nonessential spending. I would also compare other choices when a creditor can move a due date or a payment plan can avoid taking money from the next paycheck. A convenient option is not always the best one for the month as a whole.
The bottom line
In conclusion, Payactiv is a practical option for anyone looking to take more control of their financial situation. It’s packed with features that make managing money less of a headache and more of a walk in the park. Whether you need to access your earned wages or get some financial guidance, this app may be worth considering.
If you’re tired of living paycheck to paycheck and want to take the reins of your financial future, give the app a shot. It might just be the app you’ve been waiting for to make your financial life easier and more manageable. So, what are you waiting for? Check it out and see for yourself!
My recommendation comes with one condition: treat early access as a way to handle a particular timing problem, not as extra income. Before using it, check that your work arrangement is supported, understand what the app shows for your situation, and plan for the next payday with the amount already accounted for. Used thoughtfully, it can offer useful breathing room; used automatically, it may only move the same squeeze a little further down the calendar.
Frequently Asked Questions
What is Payactiv and how does it work?
Payactiv is an employee financial wellness platform that allows users to get early access to earned wages before their scheduled payday. Users can access their earned wages through Payactiv's mobile app or web platform to cover unexpected expenses or manage cash flow better. The app also offers financial planning tools, savings features, and bill payment options, making it a comprehensive financial wellness solution.
Is Payactiv safe and secure to use?
Yes, Payactiv is safe and secure to use. Payactiv uses advanced security measures, including encryption and data protection protocols, to ensure that your personal and financial information is kept secure. Additionally, Payactiv complies with relevant financial regulations and standards, providing users with peace of mind when using the platform to manage their finances.
Does Payactiv charge any fees for its services?
Payactiv does charge fees for some of its services, such as transferring earned wages to a bank account or using the Payactiv card. However, there are no hidden fees, and all costs are transparent and clearly communicated to users before any transaction. It's advisable to review the fee structure within the app to understand any charges you might incur.
Can I use Payactiv if my employer does not partner with them?
Payactiv primarily operates through partnerships with employers, enabling employees to access their earned wages early. If your employer does not partner with Payactiv, you may not be able to use the service directly. However, you can encourage your employer to consider partnering with Payactiv to provide this benefit to employees, or you can check for any standalone features that might be available to individual users.
What should I do if I encounter issues with the Payactiv app?
If you encounter issues with the Payactiv app, there are several steps you can take. First, try restarting the app or your device to see if the issue resolves. If problems persist, consult the Help or Support section within the app for troubleshooting tips. You can also contact Payactiv's customer support via email or phone for further assistance. They are typically responsive and eager to resolve any user issues.


